Producer Price index increased a seasonally adjusted 1.1% on the month (ahead of +0.7% expectations), putting the 12-month wholesale inflation rate at 6.5%.
Excluding food and energy, the core PPI accelerated 0.4%.
Taking out food, energy and trade services, the PPI accelerated 0.8%, the biggest one-month move since March 2022. On a 12-month basis, the core excluding trade services rose 5.1%, the most since October 2022.
Comparisons to 2022 wholesale inflation aside, probably not a great outlook for near-term direction of consumer prices…
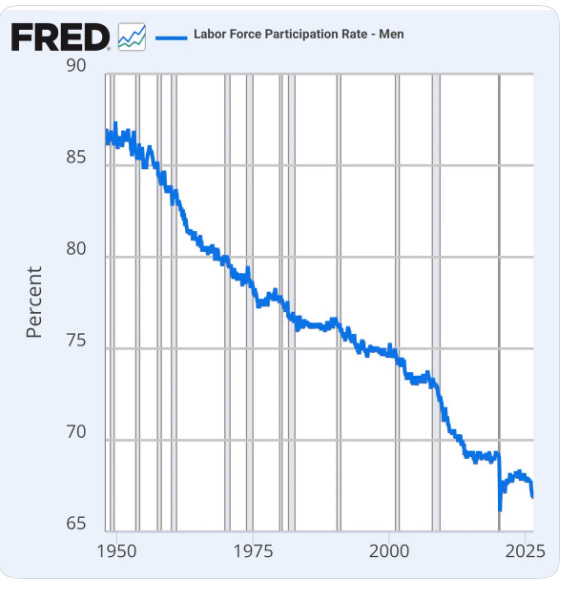
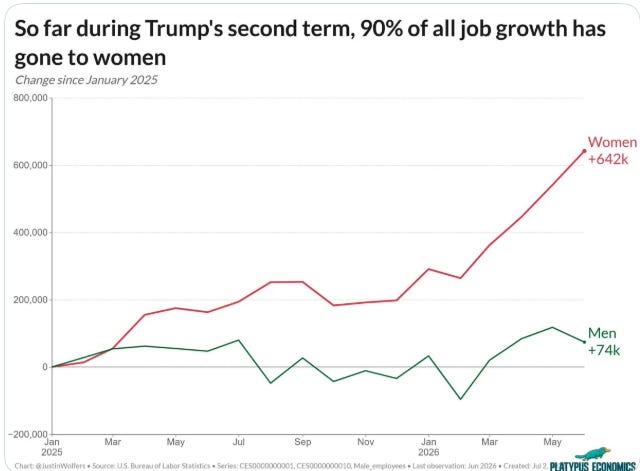
Jobs report disappointed, but more to the point lots of people aren’t working or even looking (“labor force participation rate”). Men vs women breakdown on the job market
Gas prices are more sticky than the lower now (tbd on the latest Iran attacks) oil prices. The reason is lack of refining capacity globally, and Ukraine’s successful drone attacks on Russian refineries specifically.
The most significant recent shift has been in Russia, which banned diesel exports after months of Ukrainian attacks on its refineries caused domestic shortages. Russia is the world’s second-largest diesel exporter after the US, accounting for 11% of global shipments.
In Europe, scorching heat has threatened the ability of refineries to make fuel at full capacity. Limits to the efficiency of their cooling and condensation systems means they have to cut output by as much as 15% during a heatwave.
Refiners have operated at maximum capacity in the US for months straight, running the risk of mechanical breakdowns that could stifle production.
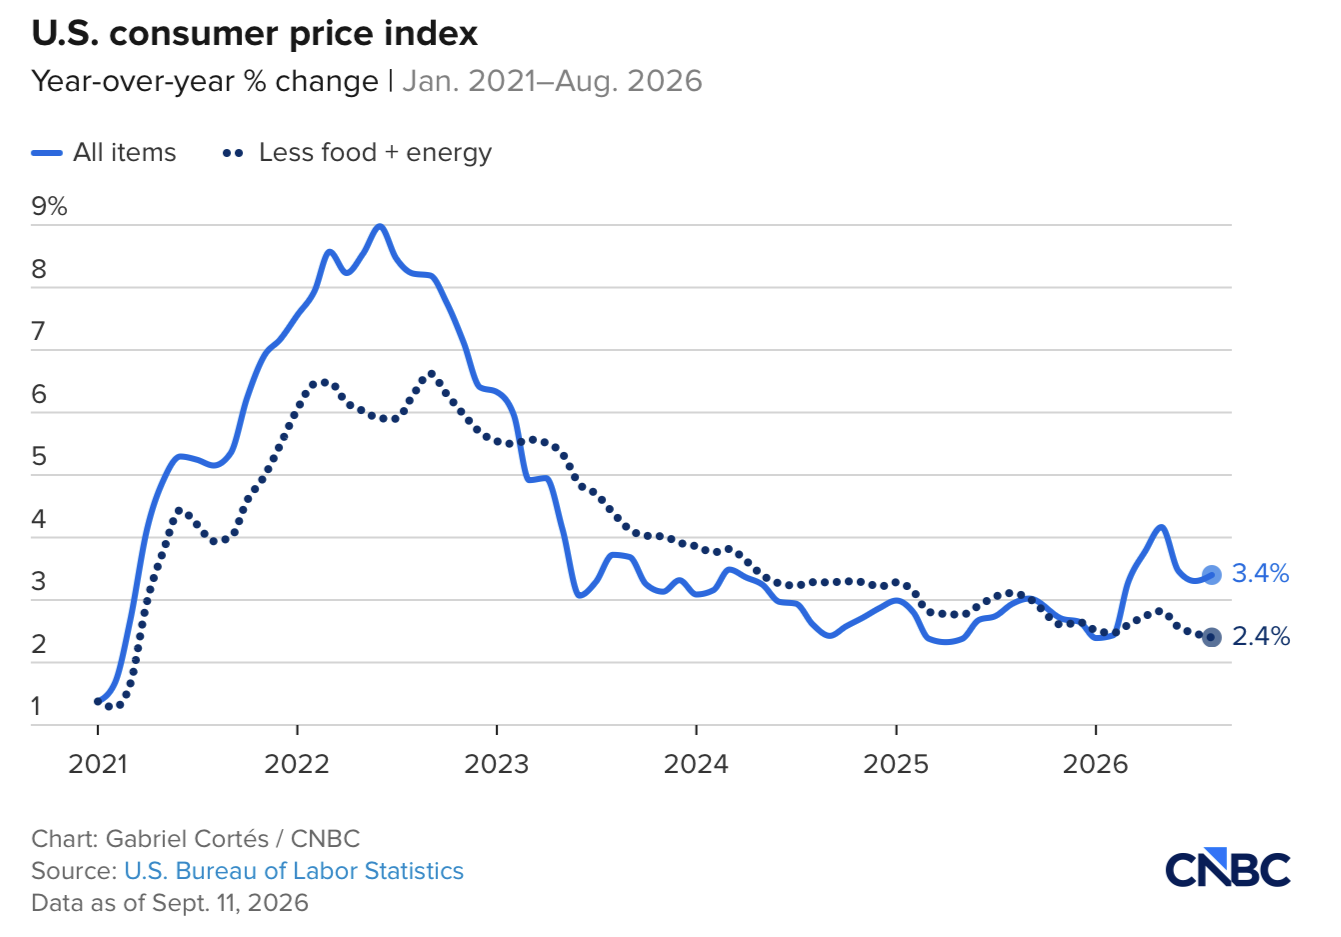
July’s consumer price index came in as expected, with headline rising 0.1% on the month and the annual inflation rate landing at 3.4%. Core CPI, which excludes food and energy, advanced 0.2% last month and 2.5% on the year. The annual rate for both headline and core CPI marked a slight decrease from June.
Sept CPI out, came in a bit higher than expected, on both overall and core measures:
US CPI (MOM) (SEP) ACTUAL: 0.6% VS 0.4% PREVIOUS; EST 0.6%
US CPI YOY ACTUAL 3.7% (FORECAST 3.6%, PREVIOUS 3.4%)
US CORE CPI MOM ACTUAL 0.3% (FORECAST 0.2%, PREVIOUS 0.3%)
US CORE CPI (YOY) (SEP) ACTUAL: 2.6% VS 2.4% PREVIOUS; EST 2.5%
GASOLINE DRIVES MORE THAN HALF OF U.S. INFLATION SURGE Gasoline prices jumped 9.1% in September, while fuel oil, including diesel, surged 15.3%. Energy costs drove more than half of the monthly CPI increase, pushing annual inflation to 3.7%. Elevated October fuel prices signal continued inflation pressure ahead of the November 3 midterms.
stocks were down and the chances of a rate hike looking somewhat more likely now (but still not that likely for Oct):
a 33% chance of an October Fed hike, up from 21%, while hold odds have fallen from 79% to 65%